All Categories
Featured
Enhancing Your Workplace Benefit Offerings
Table of Contents
On the other hand, premiums for a traditional medical insurance group strategy are pre-tax, which lowers the staff member's overall tax liability. Searching for an easy way to run payroll? Run payroll in three steps with Patriot's online payroll. Choose our Full Service payroll service, and we'll deposit and report work taxes on your behalf! Start your totally free trial now! This post has actually been updated from its original publication date of May 20, 2020.
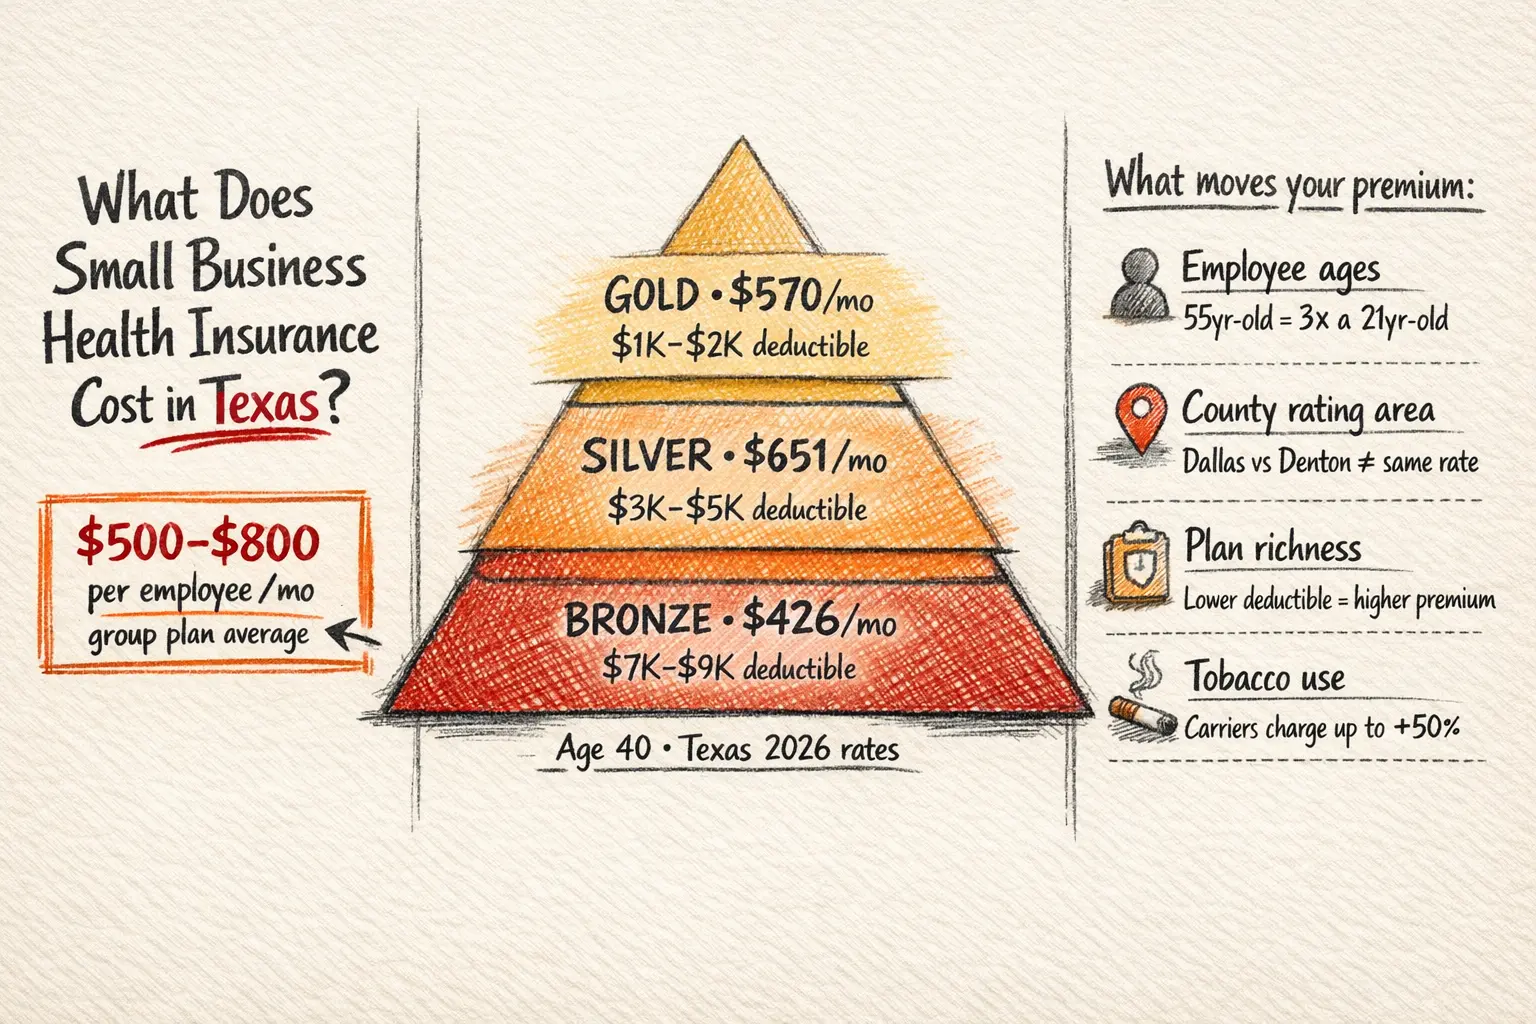
Secondly, through cost-sharing such as copays, coinsurance, and/or deductibles, which are paid when the worker uses services covered by their strategy. While all employees enrolled in the strategy needs to pay their premium (or have it paid by the employer), overall cost sharing is greater for workers who use more services.
In dollar terms, the typical annual contribution for covered workers was $1,440 for single protection and $6,850 for household protection. With time, the typical premium contribution for covered employees has actually increased. Over the last 10 years, the single coverage typical contribution has actually increased 31% and the family coverage typical contribution increased 37%.
In 2025, covered workers contributed, typically, 16% of the premium for single coverage and 26% of the premium for family protection, which resembled these averages a years ago. This is because as premiums have increased with time, both companies and workers have dealt with similar increases typically.
In 2025, 29% of covered workers at little companies were enrolled in a strategy where the company paid the whole premium for single coverage. This was just the case for 7% of covered employees at big companies. Nevertheless, 29% of covered workers at little companies remained in a plan where they must contribute majority of the premium for family coverage, compared to 5% of covered employees at big firms.
Steps to Audit Employee Wellness Plan ROI
Small companies often approach the cost of health insurance differently than large firms, often making the very same employer contribution despite whether the worker enrolls any dependents. Likewise, some large employers encourage spouses and dependents to register in other strategies, if they have access, through spousal surcharges. In addition to any required premium contributions, many covered employees need to pay a share of the expense of the medical services they utilize.
Some plans combine cost-sharing kinds, such as needing coinsurance for a service approximately a maximum quantity or needing either coinsurance or a copayment for a service, whichever is greater. The type and level of expense sharing might differ with the kind of strategy in which the employee is enrolled.
Plans typically structure their expense sharing to motivate enrollees to review their use, decreasing total usage. In the last few years, basic annual deductibles have grown in prominence in strategy design. In 2025, 88% percent of covered employees were enrolled in a health insurance which needed that an enrollee met a deductible before the strategy covered most services.
Group Benefits EscondidoTypically, covered employees at smaller firms face higher deductibles than those at big firms ($2,631 vs. $1,670). Generally, a significant share of workers dealt with fairly high deductibles. Fifty-three percent of workers at little companies and 28% of employees at big firms had a general annual deductible of $2,000 or more.

Steps to Improve Your Wellness Programs
While typical deductibles have actually not grown over the last couple of years, the growth over the last ten years outmatches the boosts in premiums, incomes and inflation. The rise in deductible costs has actually concentrated on consumerism in healthcare. Some think that increasing deductibles will put a higher incentive on enrollees to look for services, therefore minimizing total strategy costs.
The development of deductibles has actually had important consequences for the financial defense that health insurance supplies. A plethora of plans need deductibles well in excess of the financial assets of a lot of their enrollees. Instead of coinsurances and copays that build up throughout the year, deductible costs might require enrollees to finance reasonably high costs simultaneously.
Group Benefits EscondidoIn 2021, deductibles represented more than 58% of an enrollee's cost-sharing liability, which is substantially higher than 35% of enrollee liability ten years prior. The quantity of expense sharing large group enrollees face differs, especially around the number of health services an individual uses. People who have a hospitalization, or a persistent condition that needs continuous management, frequently sustain greater cost-sharing throughout the years.

Latest Posts

Integrating Payroll Insurance Policies for Modern Groups
Winning the Talent War in Your Area with EAPs
Innovative Workplace Wellness Initiatives for 2026